
Your School Is Short on Cash. Panic Is Not Step One.
When the bank balance gets uncomfortable, the answer is not panic. It’s information, priorities, and a plan.
There is a particular kind of stress that comes from opening your school’s bank account and realizing the number on the screen is considerably less comforting than you would like.
Payroll is coming. Tuition payments are still trickling in. A reimbursement you expected last week has apparently decided that deadlines are more of a suggestion. Meanwhile, the electric company remains stubbornly committed to being paid.
Welcome to a cash crunch.
In our first School Finance Insights post, we talked about why cash and profit are not the same thing. In the second, we looked at how much cash your school should keep in reserve so that an unexpected problem doesn’t immediately become a crisis.
But what if you’re already there?
A cash-flow crisis requires a different kind of financial management. Your immediate job is not to solve every long-term problem in the business. It is to understand exactly where you stand, protect the things that keep the school operating, and create enough breathing room to make good decisions.
Because while panic is a very understandable response to a dwindling bank balance, it is unfortunately not an accepted form of currency.
First, Find Out Exactly How Much Cash You Have
This sounds obvious, but when a school is under financial pressure, the first step is getting much more precise than, “There’s about $40,000 in the bank.”
You need to know what cash is actually available, what money is expected to come in, and what obligations are about to hit the account.
Start by looking at your current bank balance and the expenses due over the next several weeks. Include payroll, payroll taxes, rent or mortgage payments, utilities, insurance, debt payments, food, essential classroom expenses, and anything else that must be paid to keep the school functioning.
Then look at expected cash inflows. What tuition should be collected? Are government reimbursements pending? Are there outstanding receivables? Is there money showing in your accounting system that has been earned but has not actually reached your bank account?
Your accounting records may tell you that you have earned revenue. Your employees, however, generally prefer to be paid with money that has completed its journey to your checking account.
During a serious cash crunch, I recommend monitoring cash daily or very close to daily. This is not the season for glancing at the bank account once a month and hoping everyone involved has behaved themselves. You need current information because the decisions you make this week may affect what happens two or three weeks from now.
Next, Separate “Must Pay” From “Would Normally Pay”
When cash is plentiful, most expenses simply get paid as they come due. A cash crisis requires more deliberate prioritization. Ask what absolutely has to be paid to keep the organization operating safely and legally. Payroll is obviously critical. So are obligations such as payroll taxes, essential utilities, and expenses directly necessary for caring for children and operating the school.
Then look at everything else. There may be purchases that can wait. Subscriptions you can pause. Projects that sounded like excellent ideas three months ago but suddenly look considerably less urgent. This is the time to stop nonessential spending and protect cash for the expenses that truly matter.
This does not mean randomly refusing to pay bills. It means understanding the difference between an expense that must happen today and one that can responsibly be postponed.
And one important reminder: payroll taxes are not a source of short-term financing. The IRS is not your line of credit. Never, and I mean NEVER, consider payroll taxes to be an expense you can delay.
Collect the Money People Already Owe You
Before looking for new money, make sure you are collecting the money you have already earned. Review your accounts receivable. Which families have outstanding balances? Which invoices are overdue? Are subsidy or government reimbursement submissions complete? Is paperwork sitting somewhere waiting for someone to submit it?
I worked with one organization that had roughly $30,000–$40,000 in tuition that had not been collected. That creates a very different problem than simply not charging enough tuition. The revenue may technically exist on the books, but revenue sitting in accounts receivable is not paying Friday’s payroll.
Some payment timing is outside your control, particularly when government funding is involved. You cannot make an agency process a reimbursement faster simply by staring intensely at your inbox. You can, however, control whether your paperwork was submitted correctly and on time. You can follow up on overdue family balances. You can establish consistent collection procedures instead of discovering six months later that several accounts have quietly wandered off without paying.
In a cash crunch, receivables deserve immediate attention.
Talk to People Before the Situation Gets Worse
Cash problems tend to become more expensive when we avoid talking about them.
If you know a payment is going to be difficult to make on time, contact the vendor before it is overdue. Some vendors may be willing to extend a due date, split a payment, or temporarily adjust terms. They are generally much more receptive when you approach them proactively rather than after several unanswered invoices.
Communication with employees and families requires more judgment. You don't want to create unnecessary panic by announcing every temporary cash fluctuation to the entire school community. At the same time, if a financial issue will materially affect employees, families, services, or operations, appropriate communication matters.
The goal is neither secrecy nor oversharing. It is calm, accurate communication with the people who actually need the information.
Be Very Careful With Short-Term Financing
Sometimes a cash crunch is primarily about timing.
Perhaps you know a large reimbursement is coming in 30 days, but payroll is due next Friday. Maybe the business is fundamentally healthy, but there is a temporary mismatch between when cash comes in and when expenses have to be paid.
In situations like that, short-term financing may be one option to evaluate. A dependable banking relationship or an established line of credit can sometimes provide a bridge.
But this is where you need to slow down.
When a business owner urgently needs cash, there is no shortage of companies delighted to provide it at terms that become considerably less delightful once you calculate the actual cost. Before borrowing, understand the interest rate, fees, repayment schedule, collateral or guarantees, and the effect those payments will have on future cash flow. Most importantly, ask what will repay the debt. If the answer is a specific receivable that is expected soon, you may be dealing with a timing problem. If the answer is, “Hopefully things will get better,” you may be borrowing money to cover an underlying profitability problem. Those are very different situations.
Build a Short-Term Cash Forecast
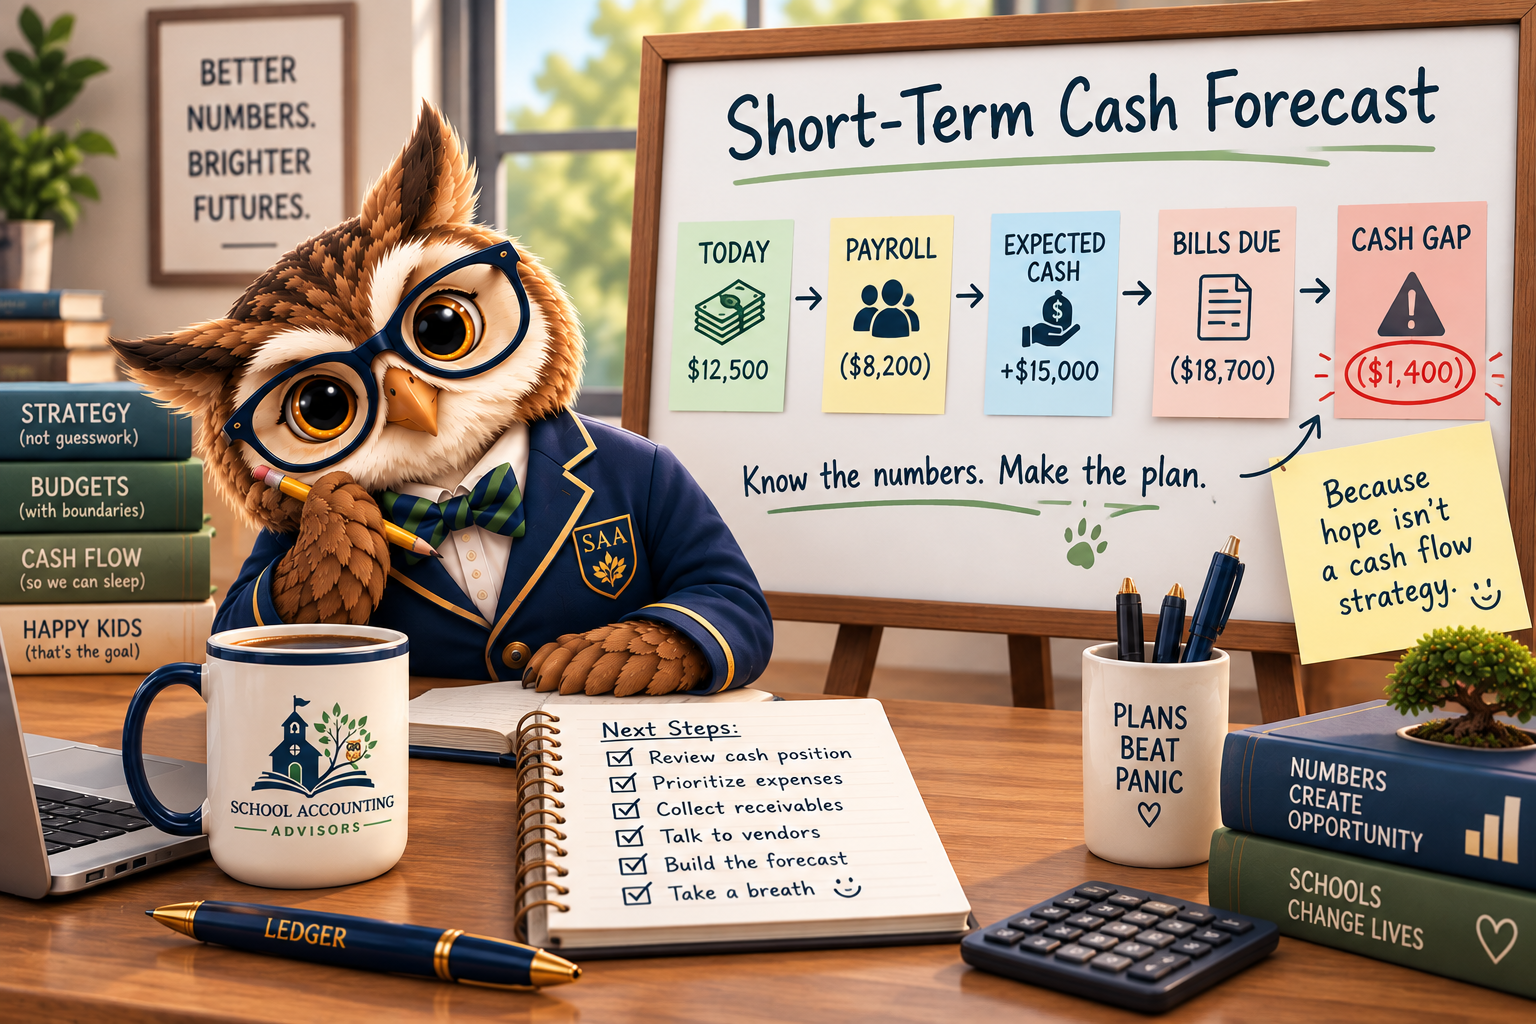
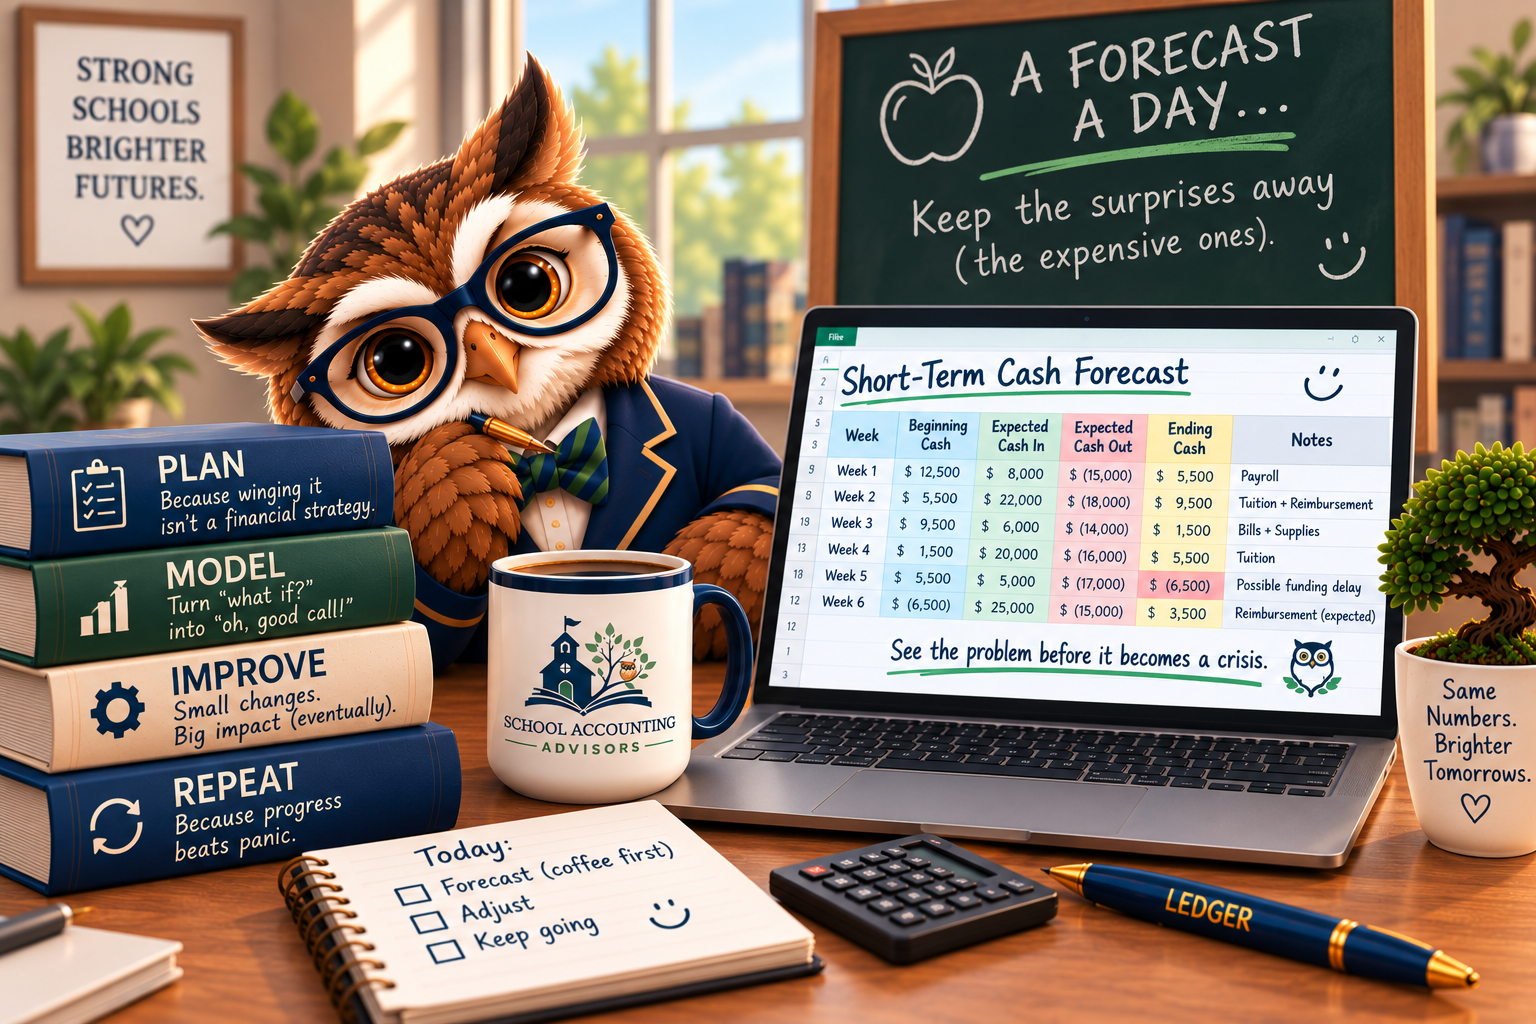
Once you know your cash position, expected receipts, required expenses, and any flexibility you've created, put all of it into a short-term cash forecast.
It does not need to be beautiful.
It needs to be useful.
Look week by week at: Beginning cash + expected cash in – expected cash out = ending cash
Then carry that ending cash into the next week. Suddenly, instead of thinking, “We're running out of money,” you may be able to say, “If nothing changes, we're going to be approximately $18,000 short during the week of October 12.” That is a much more useful problem.
Now you can ask what can change before October 12. Can outstanding tuition be collected? Can an expense be delayed? Is a reimbursement expected? Can spending be reduced? Does the timing of a major purchase need to change? Do we need to get a line of credit?
This is why forecasting matters so much. In my own school experience, seeing a potential cash crunch roughly five months ahead gave us time to control expenses and prepare financing as a backup. We ultimately didn't need to use that financing. The important part was that we had options because we saw the problem coming.
Five months gives you quite a few choices. Five days mostly gives you caffeine (and stress).
Stabilizing Cash Is Not the Same as Fixing the Business
This may be the most important distinction in the entire conversation.
Everything we've discussed so far is designed to help you stabilize cash. Collecting receivables, delaying discretionary purchases, negotiating payment timing, or using appropriate short-term financing can create breathing room.
But breathing room is only useful if you use it to figure out why the cash crisis happened. Sometimes the answer really is timing. A large reimbursement arrived late, an unusual expense hit at the wrong moment, or enrollment dipped temporarily.
Other times, the cash shortage is a symptom of a deeper problem: the school simply isn't generating enough profit to support its expenses. Once immediate cash is stabilized, you need to look at the underlying business model. In my work with schools, I tend to think about profitability as a three-legged stool: enrollment and capacity, tuition pricing, and employee pay and benefits. Those pieces have to work together.
A school cannot indefinitely solve a structural profitability problem by moving bills around the calendar. Eventually, the calendar gets suspicious.
Then Ask the Harder Questions
Once the immediate crisis is under control, this is where financial modeling becomes valuable.
How many students do you need to break even? How close are you to capacity? Are your tuition rates actually covering the cost of providing care or education? What is your labor cost relative to revenue? How much are discounts affecting your effective tuition rate? Would adding another classroom improve profitability—or simply add another room full of expenses?
Those are different questions from, “Can we make payroll Friday?”
But if you only answer the Friday question, you may find yourself asking it again next month.
A cash crisis should eventually lead to a cost-of-care analysis, break-even analysis, cash-flow forecast, and a careful look at the school's operating model. The goal isn't merely to survive this particular shortage. It's to understand what needs to change so you aren't managing the same crisis repeatedly.
And When the Crisis Passes, Start Building the Cushion
Once cash stabilizes and the underlying business is healthy, start building reserves.
As we discussed in How Much Cash Should Your Childcare Center Keep in Reserve?, I like to think about this progressively:
One month of payroll → one month of full expenses → two to three months of full expenses → eventually three to six months where appropriate.
You don't have to get there overnight.
The point of a reserve isn't to collect money in a bank account simply because accountants enjoy looking at large numbers. A reserve buys time. And time gives you the ability to respond thoughtfully when enrollment changes, funding gets delayed, an expensive repair appears, or something else inevitably decides your financial plan looked a little too peaceful.
The Goal Is to Get Out of Emergency Mode
If your school is in a cash crunch right now, start with the immediate questions:
What cash do we actually have? What is coming in? What absolutely must go out? What can wait? Who owes us money? Where do we have flexibility? And how many weeks of runway do we have?
Then build the forecast. Once you have facts instead of fear, you can make decisions in the right order. A cash crisis does not automatically mean your school is failing. But it does mean the numbers are asking for your attention. Listen to them while they're still speaking at a reasonable volume.
Because your bank balance really shouldn't have to yell.
Better Numbers. Better Decisions. Stronger Schools.
At School Accounting Advisors, we help childcare centers and independent schools understand what's happening with their cash, forecast what's coming next, and model the financial decisions that can create a stronger organization.
If you're looking at your bank account right now and wondering whether the numbers are trying to tell you something, we can help translate. BOOK A FREE CONSULT →